
Tax practice is often associated with computations, documentation, and compliance. However, a recent tax seminar offered a broader perspective. Understanding tax also means understanding the rules and procedures that govern how the Bureau of Internal Revenue (BIR) conducts audits and issues BIR tax assessments.
For tax professionals, this distinction matters. An assessment is not determined by numbers alone. Authority, deadlines, documentation, and due process can all play a decisive role in determining whether an assessment is valid.
The session, led by Atty. Betheena C. Dizon, Tax Partner at SGV & Co., together with Atty. Jules Riego, Co-Chair of the Financial Services Taxes and Tariffs Committee at AmCham Philippines, highlighted several practical lessons that tax practitioners can apply when navigating audits and potential disputes.
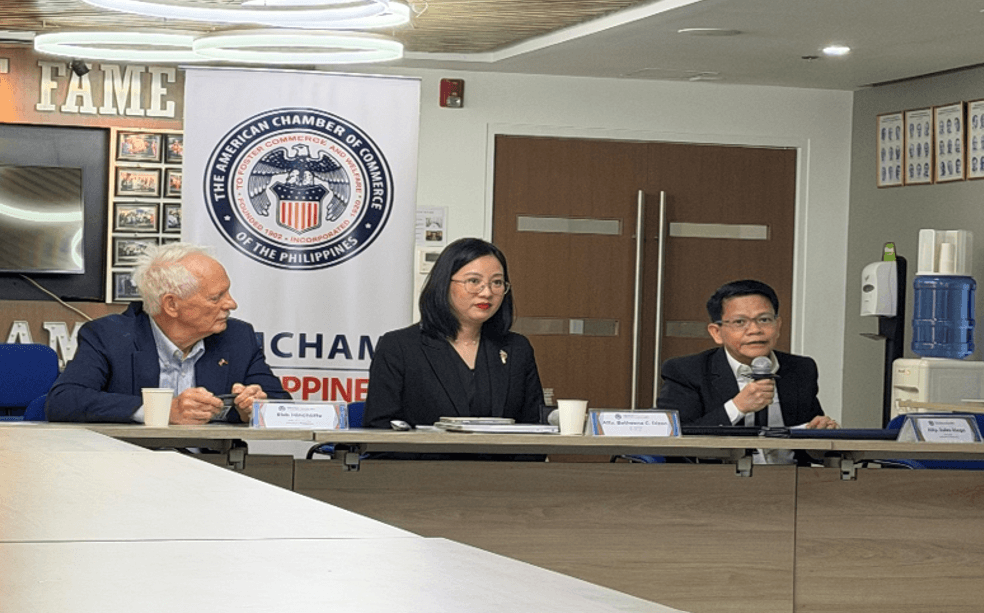
Seminar Speakers
- Atty. Betheena C. Dizon — Tax Partner, SGV & Co.
- Atty. Jules Riego — Co-Chair, Financial Services Taxes and Tariffs Committee, AmCham Philippines
For reference, tax professionals may also consult official resources from the BIR: https://www.bir.gov.ph
Understanding Prescriptive Periods for Tax Assessments
One of the seminar’s key discussions focused on the prescriptive period for tax assessments. As a general rule, the BIR has three years to assess taxes. In certain circumstances, however, a ten-year period may apply, including cases involving false or fraudulent returns.
The distinction between an erroneous return and a fraudulent one is particularly important. A mistake or misstatement does not automatically establish fraud. Instead, for the extraordinary ten-year period to apply, the error must involve deliberate or willful conduct.
Consequently, this distinction has significant implications for tax practice. An honest mistake should not receive the same treatment as an intentional attempt to evade tax. When reviewing BIR tax assessments, practitioners need to examine not only the error itself but also the surrounding circumstances.
Why Intent Matters
Practitioners should consider:
- Whether the error was accidental or deliberate
- The available supporting documentation
- The taxpayer’s actions before and after discovery of the error
- Relevant laws and jurisprudence
Why the Letter of Authority Matters
The seminar also highlighted the importance of the Letter of Authority (LOA). At first glance, an LOA may seem like an administrative document authorizing a tax examination. In reality, it also protects a taxpayer’s right to due process.
Revenue officers conducting an examination must have proper authority. Furthermore, the officers assigned to the examination should be identifiable from the LOA. If officers originally assigned to an audit are replaced without proper authority, the validity of the resulting assessment may be challenged.
This is a critical practical point. Personnel changes may seem routine. Nevertheless, they can carry significant legal consequences during tax examinations.
LOA vs. Letter Notice
The seminar also clarified the distinction between an LOA and a Letter Notice.
- An LOA authorizes a formal tax examination.
- A Letter Notice identifies possible discrepancies or information requiring review.
- A Letter Notice does not automatically replace the authority provided by an LOA.
Therefore, treating the two documents as interchangeable may create serious procedural issues.
Additional guidance is available through the BIR website: https://www.bir.gov.ph
Due Process Is Not a Technicality
Throughout the seminar, due process emerged as a central theme.
The BIR has broad powers to assess and collect taxes. However, those powers must operate within legal boundaries. Taxpayers must receive sufficient information about the factual and legal bases of an assessment. They must also have a meaningful opportunity to contest it.
For practitioners, reviewing BIR tax assessments should involve more than checking the amount being claimed.
Key Questions to Ask
- Was there a valid LOA?
- Were the revenue officers properly authorized?
- Was the assessment issued within the applicable prescriptive period?
- Did the BIR sufficiently explain the factual and legal basis of the assessment?
- Was the taxpayer properly notified and given an opportunity to protest?
These questions can be just as important as the underlying tax computation.
For legal references, practitioners may consult the Official Gazette: https://www.officialgazette.gov.ph
The Practical Importance of Waivers
Another valuable discussion centered on waivers extending the period within which the BIR may assess taxes.
A signed waiver should not automatically be considered valid. Practitioners must also verify whether the person who executed it had the authority to do so and whether the necessary requirements were satisfied.
The lesson is straightforward. Signatures alone do not settle questions of legal validity. Corporate authority, proper documentation, and compliance with applicable requirements remain essential.
Specifically, practitioners reviewing BIR tax assessments should carefully examine the execution and supporting documentation of any waiver involved in the audit process.
Connecting Compliance and Tax Litigation
Perhaps the seminar’s most significant insight was the close relationship between tax compliance and tax litigation.
Procedural rules may appear secondary to tax computations. In contrast, many cases demonstrate that procedural defects can determine whether an assessment remains enforceable.
An examination conducted without proper authority, an assessment issued beyond the applicable prescriptive period, or a failure to observe due process can have consequences that extend well beyond a procedural objection.
For tax practitioners, this reinforces the importance of taking a holistic approach. Numbers tell only part of the story. A sound review must also consider the authority behind the examination, the applicable deadlines, the documents issued, and whether the taxpayer’s procedural rights were respected.
Key Takeaways
- Authority matters as much as computation.
- LOAs play a critical role in protecting due process.
- Prescriptive periods can affect the validity of assessments.
- Waivers require proper authority and documentation.
- Procedural defects can affect enforcement outcomes.
A Broader Perspective on Tax Practice
The seminar ultimately offered a valuable reminder for professionals building careers in taxation: good tax practice goes beyond compliance with numbers.
Understanding how the BIR exercises its assessment powers is equally important. Whether assisting with a tax audit, reviewing an assessment notice, preparing a protest, or analyzing a potential dispute, practitioners must examine both the substance and the process behind BIR tax assessments.
Furthermore, the experience underscores the importance of staying informed about developments in tax law and jurisprudence. These insights strengthen technical knowledge while helping professionals identify issues with significant legal and practical consequences.
Tax compliance may begin with the numbers. Effective tax practice does not end there.
Let’s Discuss Your Business Needs
Looking for expert guidance on tax compliance, audits, workforce solutions, or professional development programs? Connect with the team at John Clements Consultants, Inc. today.

